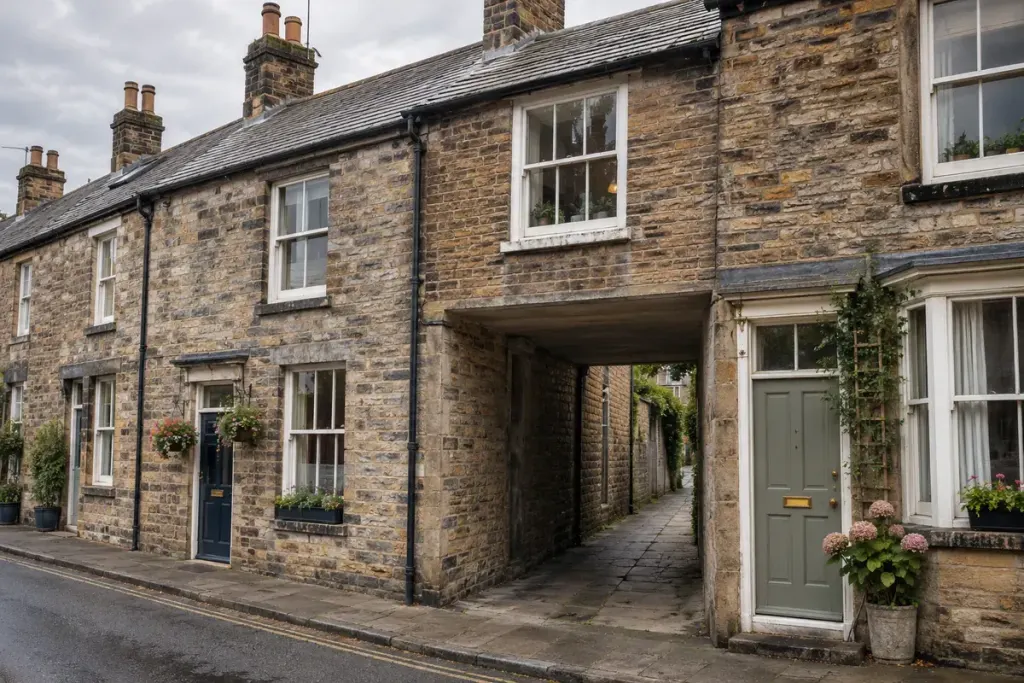
A bedroom above a neighbour’s passage can look perfectly ordinary during a viewing. Legally, however, part of the building may extend over land that belongs to someone else. In England and Wales, that arrangement can involve a flying freehold, and it deserves a clear explanation before a purchase progresses.
The Law Society’s tenure guide gives examples including rooms over passageways and basement vaults. It also notes that lenders may need further information. The term describes an ownership arrangement; it does not, on its own, tell you whether the building is defective or whether a particular mortgage will be available.
Connect the paperwork to the physical space
Ask your conveyancer to identify the affected area on the title documents and explain it in relation to the rooms you have seen. A photograph of the passage or overhanging room can help make the discussion concrete, but it cannot establish the legal boundary by itself.
Useful questions include:
- What rights support and protect the part crossing the boundary?
- How would someone gain access for inspection or repair?
- Who is responsible for the relevant structure?
- What does the proposed lender require for this exact arrangement?
The RICS Home Survey Standard identifies flying freeholds among matters that may require investigation by a legal adviser. A surveyor and conveyancer therefore have connected but different questions to answer.
Test the explanation with a practical scenario
Imagine the underside of the overhanging room needs repair. Where would scaffolding go, who would be contacted, and which document gives the necessary rights? This is a discussion prompt, not a legal conclusion. It helps reveal whether the explanation you have received is usable rather than merely reassuring.
Keep the written answers with the purchase papers. Do not assume an insurance proposal creates physical access or settles a maintenance disagreement. Ask the professionals handling your transaction to explain any proposed solution, its limits and the lender’s position before you commit.