A house can have a clean inspection report and still sit in an area exposed to flooding. It can also fall outside a mapped high-risk area while showing evidence of drainage problems. These observations answer different questions, so one should not cancel out the other.
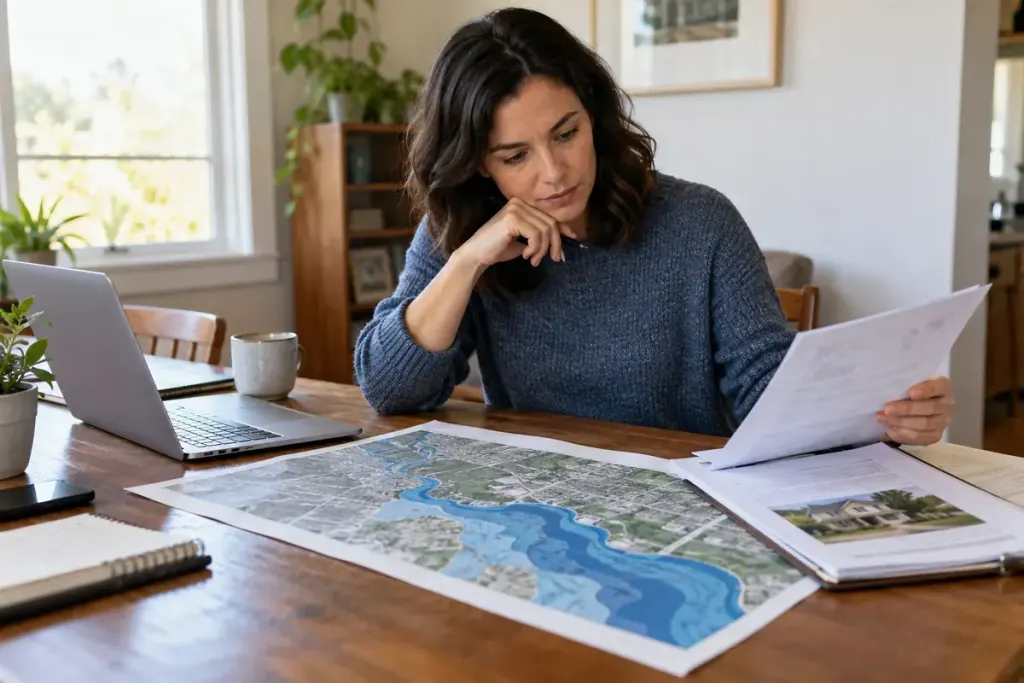
For US properties, FEMA’s guide to reading a Flood Insurance Rate Map explains the map’s zones and associated information. The map is a starting point for understanding mapped flood hazards, not a survey of every defect in an individual building.
Keep two sets of questions
For the map, record the address searched, the panel or source, its effective date and the zone shown. Ask the relevant local authority whether amendments or other local information affect the property. Save the record you actually reviewed, rather than a cropped screenshot with the legend missing.
For the inspection, ask what was examined and what was outside scope. Visible staining, the ground around the building and accessible drainage features may prompt further investigation, but an ordinary inspection is not automatically a specialist flood-risk assessment. Read the limitations as carefully as the findings.
- Does the seller provide a history of water entry, repairs or insurance claims?
- Are there documents explaining work to drainage or the building’s lowest level?
- Would a qualified specialist need to investigate an unanswered question?
- What cover and exclusions does an insurer actually offer for this address?
These are research prompts, not a statement of disclosure law. Disclosure duties, lending conditions and insurance requirements vary by jurisdiction and transaction.
Resolve contradictions before relying on them
If an agent says “no flood concern” but a document contains a flood reference, request a written explanation tied to the relevant source. Likewise, a dry viewing day cannot settle a question about heavy rainfall. A useful buying file preserves both the mapping evidence and the building evidence, with unresolved points clearly marked for professional follow-up.